Category: Finance

The Future of Content

A fascinating piece by John Maudlin.

I came across John Maudlin’s web site some time ago and ended up subscribing to one of his Blogs, Outside the Box.  To be frank, much of what John writes is a little bit too technical for me but this item did catch my eye to the extent that I read the item in full and was intrigued by it.

The article was called, “Apple, Google, NewsCorp and the Future of Content”  You can read it directly here.  But just to whet your appetite, here’s a small extract of what is primarily an interview with Michael Whalen:

In this issue of The Institutional Risk Analyst, we speak to Michael Whalen, [Emmy] award winning composer and new media observer about the outlook for the business of creating and delivering content.  Since graduating from Berklee College of Music, Michael has taught a business for music class that has saved thousands of young artists from making terrible mistakes with content and other contractual rights.  Think Frank Zappa and Warner Brothers.   And yes, Michael is IRA co-founder Chris Whalen’s younger brother.

and later …

Whalen: Frankly, I think we’re going back to the 19th century in terms of the “status” of artists. They’ll be figureheads. Imagine: like Paris or Vienna of the 1900s, we’ll have wealthy patrons and small clutches of people who support the art of “real” artists. In this environment, the work we will try to sell is simply a loss leader and an inducement for us to perform or create a “custom” song, TV show or film… Yup, it’s all here now… What will be really interesting is what happens next… I am not pretending to be the “Grim Reaper” but I think the record business, the film studio system and the television networks are over as we think we know them. I think there is a new business emerging in gathering creative investment, content and creative marketing…. It will be in a structure that’s more akin to a stock market than the traditional structure we’ve seen for artistic and creative content and the platform for it will be the digital ocean we have already discussed. Based on the “buzz”, there will be a “futures” market and the idea is commoditized and funded in days – not months or years. For decades, most record companies and networks have been little more than funding sources for artists – now the truly visionary artist won’t even need these ancient businesses – the market itself will generate everything it needs to create content efficiently. It’s a little overwhelming the change that is here now vs. five years ago and that will be coming in torrents in the next few years. Amazing.

Read the full interview here – I promise you won’t regret it.

By Paul Handover

Fairness in society

Very difficult times ahead but a fairer social order could be one outcome.

As is so often the case, a number of different lines of thought come together once again to highlight the pressures on society and my belief that we are in the ‘zone of change’ between the last 40 or 50 years and what is ahead for western societies.  There is no question that these are very difficult times as, I presume, all phases of change have been over many centuries.

On the 28th October there was a Post on Learning from Dogs about the recent book from Will Hutton, Them and Us.  That book masterfully articulates the core issues in British society arising out of some fundamental economic policy errors and the very difficult times that are being experienced right now.

The British are a lost tribe – disoriented, brooding and suspicious. They have lived through the biggest bank bail-out in history and the deepest recession since the 1930s, and they are now being warned that they face a decade of unparalleled public and private austerity.

As if to underline the fact that the economic situation is far from recovery, despite what is being promoted, here’s a recent article from Washington’s Blog. Almost impossible to take an extract that conveys the essence of this powerful (and scary) article – so just go here and read it.  Or if you haven’t the time here’s a taste:

SATURDAY, NOVEMBER 27, 2010

It’s Not Just the “Peripheral” European Countries … Financial Contagion Could Spread to “Core” Eurozone Countries and the U.S.

CNN notes:

Americans will not be spared if there’s a recession in Europe, even if U.S. bank exposure to European government debt is relatively limited.

SNIP

The European Union is the second largest market for U.S. exports, behind only Canada. The EU bought about $175 billion in U.S. goods in the first three quarters of this year. That’s up about 8% from a year ago.

So worsening problems in Europe will clearly be a drag on the U.S. as well.
Niall Ferguson, Marc Faber, and SocGen’s Edwards and Grice predicted 9 months ago that the European debt crisis would eventually spread to America.

But the question of what country the “contagion” might spread to next is really the wrong question altogether.

The real question is whether the wealth of the people around the world will continue to be shoveled into the bottomless pit of debts held by the big banks, or whether the people will prevail and the giant banks and bondholders will be forced to take a haircut. See this, this and this.

So back to the issue of fairness.  There is no escaping the consequences, still playing out, of the ‘spend now, pay tomorrow’ culture of the last 30 or 40 years so then the main issue is how do we mitigate the consequences for those who are most exposed to some of less prettier aspects of modern life.  Ponder on that question while you read this recent piece from Open Democracy.

Fairness and the cost of life for the poor in Britain

Brian Landers, 26 November 2010

Most Britons had “never had it so good” despite the “so-called recession” declared Lord Young of Graffham.  His words were immediately disowned by David Cameron, who fired him. But in reality Young was only articulating what he and his circle are experiencing and privately believe.

For example, on the BBC’s Sunday morning Broadcasting House on 21 November, Lord Charles Powell who was Margaret Thatcher’s advisor, complained, “unfortunately he said the wrong thing. In terms of fact what he said was probably right, with interests rates low people are not particularly badly off at the moment. But some people are very badly off and it is insensitive, I suppose, to suggest that everyone is not doing too badly at this time. It does show that you can’t speak the truth in politics anymore you have to defer to what is politically correct”.

Well, there is another truth: that for thousands of pensioners and not just “some” of them, negative real interest rates on their savings are becoming a disaster. Even though for the heavily mortgaged wealthy, low interest rates do indeed make them much better off.

What Young’s comments illustrate, therefore, is that when we consider equality and inequality we need to look at expenditure patterns, which can be just as important as differences in income.

Historically debates on social equality focus overwhelmingly and inevitably on inequalities of income. We read, for example, that according to a study by Incomes Data Services chief executives of the UK’s 100 largest companies are now paid on average 88 times the pay of typical full-time workers and that this ratio is getting worse. Last year the multiple was 81 times and ten years ago top bosses took home 47 times the average wage.

But in addition to their income being a lot lower the poor also suffer more because life costs them more. There are two issues, one obvious, one less so.

The primary issue is one of fairness. Three for the price of two supermarket offers are great value only for those who can afford to buy two; those who can only afford one end up paying 50% more per unit. Is that fair?

Another supermarket example which received widespread but soon-forgotten newspaper coverage earlier this year is more subtle. Tesco owns three convenience store brands in this country: Tesco Express, Tesco Metro and One Stop. An enquiry in 2006 found that the corporation was charging more than 20% more for the same products in its One Stop stores than in its Tesco branded stores. Tesco responded that it was bringing prices down in One Stop but in 2010 further research showed that One Stop prices were still 14% higher than prices for the same product in the rest of Tesco. One Stop typically operated in less attractive (that is poorer) areas where there was no competition from other mega-corporations and where therefore significantly higher prices could be charged. Again that raises issues of fairness.

If such unfairness is somehow familiar there is a further layer that goes beyond fairness: we live in a society where in many tiny ways the poor actually subsidise the better off through the way patterns of expenditure are organised by the market place, (i.e., not just by providing cheap labour).

Consider for example the cost of owning a car.  Bernard Jullien of the University of Bordeaux analysed published data on household expenditure and trade data from car distributors (See Competition and Change 6, 2002). He showed that richer consumers were being cross-subsidised by poorer consumers. Distributors in France (and almost certainly elsewhere) were following a conscious policy of keeping new car prices lower to increase their market share. Then then marked up the prices of spare parts and maintenance to maintain their overall profit levels. Jullien found that the unintended consequence was that well off customers, who were more likely to buy new cars, ended up being subsidised by less well off customers who typically bought second hand cars that needed more frequent repair.

There are more examples if the term “well off” is extended to include corporations. The cost of producing and distributing the electricity needed to power a light bulb is the same whether the bulb is in a private house or in the office of a mega-corporation – and yet the corporation will undoubtedly pay far less. Quantity discounts typically reflect the purchasing power of the buyer rather than any scale economies for the seller.

What are apparently rational pricing strategies have the unintended consequence of ensuring that poor people pay more than the well off in ensuring the overall profits corporations need.

Then there is time. Time budget surveys have shown, for example, that the poor take much longer per mile to get to work than the rich because the forms of transport they use are typically much slower. Similarly the poor have to devote more time to food shopping and a host of other activities.

There is nothing conspiratorial about the way that the poor fare worse than the rich. Often it is just the accidental by-product of perfectly sensible business decisions. Indeed in some cases there may even be wider social benefits. Improved stock control with Just-In-Time inventory techniques and Call-Off procurement contracts has ensured that waste in many industries has been sharply reduced; it is unfortunate that in food retailing one consequence is that end-of-day price reductions on perishable products are now less common, again hurting the poor more than the rich.

What can be done to mitigate these expenditure inequalities? First, they deserve to be highlighted, if only because, like so much else, they are beyond the experience of the multimillionaires in and around the cabinet. Second, and especially if we are going to talk about Big Society and us being ‘all in it together’, we need to think about economic models that build into their measures of success their consequences for all of us.

[Published with the permission of Brian Landers and openDemocracy.net under a Creative Commons licence.]

By Paul Handover

More on Them and Us

Will Hutton’s book continues to impress me; greatly.

On 28tTh October, I wrote an article about Will Hutton‘s impressive book, Them and Us.  I had got to page 120 or thereabouts and could resist no longer the urge of reading the book to the end before commenting on Learning from Dogs.

Now I am reading through page 260 and, again, find myself incapable of waiting until the book is completed before offering further thoughts!

Despite being very optimistic about the long-term future, I sense that the period that we have been in since 2008 may turn out to be one of the darkest in recent history – I touched on this aspect in a recent post called Faith in a (new) future.

One of the things that strikes me is the complete lack of openness from the British Government about the likely growth scenarios over the next decade.  Here was how the latest ‘growth’ figures were presented a couple of weeks ago, “The economy grew by 0.8% in the three months to September – double the rate that had been predicted by analysts.”

UK output increases by 0.8 per cent 4Q 2010

But here’s Will Hutton,

Britain is going to be much poorer than it anticipated just a few years ago.

and a couple of sentences later talking about economists Carmen Reinhart and Ken Rogoff,

They paint a sober picture of prolonged loss of output, high unemployment and depressed asset prices, and warn that there is no precedent for what happens after the kind of global crisis through which we have just lived. (My italics)

Hutton says that growth would need to accelerate to 3.25 per cent in order for output to reach its predicted level if the recession had not taken place.

He then says that a more plausible scenario if growth remains at 2.75 per cent (average level in recent years leading up to the credit crunch) “then it might never recover sufficiently to converge with the old trajectory.”

Hutton continues,

However, even that may be optimistic.  The reality is that between the economic growth troughs of 1991 and 2009, growth in Britain actually averaged just over 2 per cent.

That would lead to a cumulative loss of output of more than £5 trillion!

It could be even worse.  The economics team at Barclays believe that is it perfectly plausible for growth to average just 1.75 per cent for the first half of the current decade.

And all of this before the huge budget cuts announced by the UK Coalition Government start to bite!

So the reality is that we are a long way away from any form of real recovery, despite what the politicians are saying!

What is so impressive about the book is that Will Hutton is meticulous in his research (there are 23 pages of referenced notes at the end of the book) and from Chapter 9 starts setting out how Britain “has the opportunity to put things right fast.”  So this is a book from a well-respected author that sets out carefully and logically the cause of the recession and then presents some powerful options for change.

The bottom line is that Britain has to be a much more fairer society. Not just Britain.  Here’s an extract from a recent posting on Tom Engelhardt’s Blog. Tom is the author of the book, The American Way of War.

I’m no expert on elections, but sometimes all you need is a little common sense.  So let’s start with a simple principle: what goes up must come down.

For at least 30 years now, what’s gone up is income disparity in this country.  Paul Krugman called this period “the Great Divergence.” After all, between 1980 and 2005, “more than 80% of total increase in Americans’ income went to the top 1%” of Americans in terms of wealth, and today that 1% controls 24% of the nation’s income.  Or put another way, after three decades of ”trickle-down” economics, what’s gone up are the bank accounts of the rich.

In 2009, for instance, as Americans generally scrambled and suffered, lost jobs, watched pensions, IRAs, or savings shrink and houses go into foreclosure, millionaires actually increased.  According to the latest figures, the combined wealth of the 400 richest Americans (all billionaires) has risen by 8% this year, even as, in the second quarter of 2010, the net worth of American households plunged 2.8%

Change is definitely overdue.

By Paul Handover

Will Hutton, Them and Us

Changing Britain – Why We Need A Fair Society


Will Hutton


I have been reading Will Hutton‘s latest book for the last couple of weeks and am now through the first 5 chapters, at the time of writing this Post!  To my mind, it’s a very powerful and extremely well-argued summary of the sickness that has engulfed Britain, and by implication, other countries who have had similar experiences over the last 20 years.

There was a long extract published by the Guardian on the 26th September 2010 which gives one a good feel for the book.  Here’s how that extract starts:

The British are a lost tribe – disoriented, brooding and suspicious. They have lived through the biggest bank bail-out in history and the deepest recession since the 1930s, and they are now being warned that they face a decade of unparalleled public and private austerity. Yet only a few years earlier their political and business leaders were congratulating themselves on creating a new economic alchemy of unbroken growth based on financial services, open markets and a seemingly unending credit and property boom. As we know now, that was a false prospectus. All that had been created was a bubble economy and society. Yet while the country is now exhorted to tighten its belt and pay off its debts, those who created the crisis — the country’s CEOs and bankers, still living on Planet Extravagance, not to mention mainstream politicians — all want to get back to “business as usual”: the world of 1997 to 2007.

There are many, many sentences in the book that have one gasping for breath.  One of them that particular struck me was one on Page 13, see below for the sentence in italics.  But let me include sufficient text to put the sentence into context:

Today, philanthropy or living according to a particular moral code does not confer status.  Only money is able to do that.  People start to question whether vocational career choices – in farming, teaching, medicine or science – make any sense when society rewards them so lowly while rewarding finance so high.  Material values start to crowd out altruism, philanthropy and restraint.

Then comes this staggering reflection:

Two incidents in September 2007 highlighted the new values.  Lance Bombardier Ben Parkinson, who lost both legs after a landmine exploded in Afghanistan, was offered £152,000 compensation by the Ministry of Defence.  The very same week, Eric Nicoli left his job as CEO of EMI – having failed to turn around the company – with a pay-off of £3 million. [My italics]

Earlier, on page 6, Hutton writes of Richard Lambert, head of the Confederation of British Industry, the CBI as having said in March 2010, “for the first time in history officers of a company can become seriously rich without risking any of their own money.”   Here’s another piece from that extract published in the Guardian:

We need a shared understanding of what constitutes fairness in order to restore our society. At present, there is none. The rich argue that it is fair for them to be so wealthy, in much the same way as Athenian noblemen believed that their riches were signifiers of their worth. They believe they owe little or nothing to society, government or public institutions. They accept no limit or proportionality to their wealth, benchmarking themselves only against their fellow rich. Philanthropic giving is declining; tax avoidance is rising; and executive pay is rising exponentially. All three are justified by the doctrine that the rich simply deserve to be rich. Meanwhile, the poor, in their view – and that of a virulent right-wing media – largely deserve their plight because they could have chosen otherwise. The mockery of chavs is premised on the assumption that they could be different if they wanted to be. The poor could work, save and show some initiative. So why should we indulge them by giving them state handouts?

This lies behind the arrogance with which bankers still defend their bonuses, in spite of everything that has happened over the past few years.

OK, you get my drift! I could go on and on but, hopefully, my point is made.  This book by Hutton is going to be another of his classics and may well be seen as the ‘tipping point’ when society looks back in a decade’s time with that wonderful 20:20 hindsight!

Finally, are there other conclusions to be made of Hutton’s approach?  Yes, of course.  Reading the comments posted on the Guardian web page will show you many.

By Paul Handover

Is it me…

…. or have we all gone stark, staring mad!

Sorry, in a bit of a rant mood just now.

I read widely many Blogs out there because it seems that this channel is one which is more likely to offer real, valid commentaries on what is going on at present with regard to the economic crisis, that is the crisis in the broader sense.

Here’s a recent piece from Baseline Scenario about the US Federal Reserve.  Here’s how that piece ends:

Regulation remains largely ineffective (in fact, the industry has managed to demonize the word), the big banks are too important to fail, and interest rates are low across the yield curve. The Fed provides downside protection and there is no effective limit on the amount or nature of risks that the private financial sector can take. This is a recipe not for stagnation but rather for a metaboom in which we will receive warnings, including painful recessions – but consistently ignore them.

The 1920s opened with an 18-month recession, an eerie parallel to the 2007-9 experience. It ended with the Great Crash of 1929.

Then across the way we have a piece on The Daily Beast about Summers. I quote from the first two paragraphs with their permission (thanks guys.)

Washington is swirling with the usual rumors—the White House’s man was pushed! He jumped! But Summers is leaving because he made sure real reform was discussed—but not accomplished.

Thomas

The rumor that come November, when the mid-term elections are history, Lawrence Summers, administration’s quarterback on economic matters, will leave the White House, has been confirmed. The usual presumptions have been put in play: Summers is weary of the job; the president and his men and women feel the need for a new pair of hands under center; the man has done well; the man has done badly. There is no indication that, like Bush II’s ill-served first Treasury Secretary, Paul O’Neill, Summers is being canned for speaking truth to power. That is not the man’s style, not—let it be said—that there’s much evidence that the administration has better than a shaky grasp of the practical truths of American financial and economic life in the Age of Goldman Sachs.The bottom line is that we can expect the usual judgemental blahblahblah to grow in volume and marginality on the talk-show and Op-Ed circuit as the day calendared by the media for Summers’ leave-taking approaches.

Now go across to the article and read it in full. Read why Michael Thomas, the author and no stranger to Wall St., describes Summers as someone who “saw to it that the talk was talked, but the walk was never walked.”

And I’ll close by repeating a comment I made to the Baseline Scenario article:

I don’t have the knowledge to respond to Simon’s excellent Post in detail but his comments reinforce what feels like a constant throbbing in my mind – how can the citizens of so many countries have abdicated so much interest and concern in how they/we are governed. Wish I had even a clue as to the answer to that question.

Significant social unrest would be very scary – the ‘law’ of unintended consequences and all that – but there are times when I wonder if this, in the end, might be the only form of real progress for the hard-working, tax-paying majority.

End of rant! 😉

By Paul Handover

Not quite so ‘Irish’

“You’ve got to do your own growing, no matter how tall your grandfather was.” Irish quotation.

In England, inexplicable happenings are commonly ascribed to being ‘Irish’! It’s meant in a loving way; there is a great deal of warmth towards the different ways that Irish people appear to see the world.  But what is facing Ireland (and other countries) as a result of some distinctly unfunny goings-on in the USA is potentially hugely damaging.

To many the way that the world has descended into a dark, economic abyss, which is likely to affect us all in so many ways, and in which we are going to remain for a long time (a la Japan?), is also inexplicable.

Thus a chance comment from Norm Cimon to a recent post on Baseline Scenario set off a chain of discovery that for me has been very interesting.  Here’s how it ran.

I have subscribed to Baseline Scenario for some time.  It describes itself thus:

The Baseline Scenario is dedicated to explaining some of the key issues in the global economy and developing concrete policy proposals. Since it was launched in September 2008, this blog has been cited by virtually every major newspaper, Internet site, and blog covering economic and financial issues.

It’s a great resource.

A recent Post on Baseline Scenario, Irish Worries For The Global Economy, had already attracted 135 comments at the time of writing this post.  A recent one was from a Norm Cimon, who is described in Linked In as the owner of Info Synchronicity LLC.  This is what he said:

That is the other side of the coin. William Black has been lucid on this topic, and clear on the morality of the current age and how to fix it. Put people in jail and let everyone know why they were sent there. If you want to change perceptions then change the reality. The anger of the general public and the disdain of Wall Street are tied to that one issue. No one has paid for the crime of the millenium and everybody knows it.

And included was this recording of Bill Moyers interviewing Bill Black, the author of The Best Way to Own a Bank is to Rob One.

Here’s the interview:

However, there’s more to this discovery than the YouTube video.  If one clicks on the link behind Norm Cimon’s name on that Baseline post, then one is taken here.  It’s a pdf of a paper written by Norm Cimon entitled, “Computing Power and Human Greed.” It seems to me to explain the tools, for want of a better word, that enabled the American banking system to behave in the way that Bill Black so roundly condemns in the Bill Moyer interview.  Here’s how Cimon ends his paper:

With networked computers now cast by all organizations, including the financial sector, into the role of wizard-behind-the-curtain, we all live in Oz.  It’s long past time we pull back the veil and call a halt to the mindless application of this supreme and supremely dangerous creation before the damage gets any greater.

Unfortunately, there isn’t a date to the paper but my guess was that it was written late in 2009. Whatever the date, it is a very apt observation.

Where do we go from here, I ask?

By Paul Handover

I salute this guy!

Karl Denninger of Market Ticker is brilliant

Karl D

I say that not because I have sufficient financial knowledge to evaluate his writings from a technical point of view but because he puts in huge effort, I mean hundreds of hours a month, to support his perspective.

Anyway, do bookmark his website/blog – it’s here.

An article published on the 10th demonstrates both Denninger’s commitment to his audience and some very specific dangers potentially coming out of Europe.  Called “A Round-Up Of Current Idiocy” it includes this conclusion:

Since we keep drinking more as an economy (debt and deficits) the violence and incidence of these “undesirable outcomes” is going to continue to increase.  We had one nasty in 2000, and then again in 2007.  From the so-called “recovery” (2003) to the onset of the last mess was about four years.  We’re now about two years in from the so-called “bottom” of this latest train wreck (Lehman), and if we keep on-path, and we are as the below chart shows, our fuse should go inside the box for this next mess somewhere between now and the end of 2011.

I hope you’re ready, because this next one, coming with no real recovery having taken place in employment or private economic activity, may be the one that takes us well beyond the misery we suffered in the 1930s.

And if it does, it will be our – that’s right – our – fault, since we simply will not accept that there is no such thing as a free lunch.

Note the copyright please.

Despite it being quite a technical piece with some aspects that weren’t clear to me, no surprise!, it’s still got many important messages for all those concerned about our savings and assets.  Do read it.

Well done, Karl.

By Paul Handover

Colbert Good, Keynes Not So Smart

Another hugely interesting article from Patrice Ayme

Patrice is a good friend of this Blog so it pleases me very much to point you towards a recent article on Patrice’s own Blog.  Here’s the abstract:

Obama is well on his way to become one of the most unaccomplished presidents of the USA, ever. This is made worse, because we are at a crucial juncture of history, and the USA is in leadership position. When the car is travelling fast, and the leader is asleep at the wheel, it will not just end in the ditch.

The little smoke and mirrors Obama threw up, will be easily reversed by the republicans, as planned. So, in the end, Obama will turn up as just an extension of Bush, without the smirk… nor the originality. By choosing the same ideological, Goldman Sachs team, that implemented plutocracy under Clinton, Obama asked those who put the car in the ditch, to get it out, not understanding that they were still drunk in their quest to selfish profit.

This story presently unfolding has been seen before; it was Great Depression II, the great depression of the 1930s. It was the stall after the deliberately engineered bubble of the 1920s.

The West got out of it by massive state enforced job programs, started under president Hoover (Hoover dam, Empire State building, etc,) and pursued by FD Roosevelt (Grand Coulee dam, etc.) and Hitler (Autobahn system, copied by Eisenhower in the 1950s, and everybody else since).

Millions got employed directly by the government and the massive mobilization of WWII did the rest, followed by the GI Bill in 1945. Europe had massive state organized and financed economic activity, led by the US Marshall plan (Marshall was the US chief of staff during WWII, and Secretary of State of Truman). Europe, traumatized by what had happened also made important institutional changes, oriented towards welfare, such as free health care. Sully’s plan of circa 1600 for a “Very Christian Council of Europe” was also implemented.
clip_image002

(Labeling used on aid packages.)

The Marshall Plan (officially the European Recovery Program,ERP) was the primary program of the USA for rebuilding and creating a stronger economic foundation for the countries of Europe (1947–51). Efforts focused on modernizing European industrial and business practices using high-efficiency American models (themselves learned from French industrialists to implement American production of the 75mm gun, the mainstay of French artillery in WWI).

All this help and investment, in the USA and Europe, was paid bymarginal tax rates on income as high as 90% in the USA (under US president Ike).

Right, now, instead, the richest Americans pay the lowest tax rate (15%), and wealth has not been so concentrated in a century (a century ago, great spaces and freedom were another form of wealth, at least in the USA, which have now disappeared).

Starting in 1996, a succession of ever larger bubbles, following part of Keynes’s ideas, has injected more and more money in the economy, money which came neither from savings nor production, but mostly borrowed from aliens, and, increasingly, the Chinese.

Robert Reich (UC Berkeley), who lost to Robert Rubin (Goldman Sachs) the debate on the economic strategy to pursue in the Clinton administration, wrote an essay in the New York Times, “How to End The Great Recession”, reflecting the approach that wealth needs to be redistributed. Reich mentioned what I have long observed: the real (inflation adjusted) median income has been going down for thirty years now. This is worse than what happened during Great Depression II. So this is Great Depression III, not just another recession.

I approve of Reich’s anti plutocratic approach, of course. As he says: “The Great Depression and its aftermath demonstrate that there is only one way back to full recovery: through more widely shared prosperity.”… However, this is not the whole story.Redistribution is good, however production is necessary.Keynes, as we will see, is about throwing money to the people, as the Roman emperors invented. That is not about meaningful employment.

Obama’s ineptitude is not all his fault. The economic advice he got, even from his opponents, has been terrible. For example, Krugman, whom I approve a lot of, wanted, like Romer (the ex-chair of economic advisers) a bigger stimulus. And so did I.

But stimulating what? How? To which aim? Most of Obama’s stimulus was wasted on short term alleviation of long term structural defects, exactly the sort of trap one does not want to fall into (French socialists fell into that very trap in the recent past, with the result that the income tax started to fully go to paying the interest on the French national debt).

The USA stimulus ought to have targeted to jump start a big energy infrastructure first, followed by a massively innovative scientific industry, modeled after the military industrial complex (the only thing the USA does really well nowadays, besides plenty of hot air). Instead, the debate in economic theory has been pretty much Keynes (somewhat of a neo-stupid, see below) versus Hayek (a pro-plutocratic neo-fascist who influenced the Chicago school’s meta principle that GREED, AND ONLY GREED, MAKES GOOD).

However, the military-industrial complex of the USA, by now, by far, the most competitive part of its economy, is not run according to Hayek, or Keynes. It is run along the lines defined by Jean Baptiste Colbert. That ought to be a hint, but no main stream American economist has picked it up.

American economists in good standing do not know who Colbert was, perhaps because he thrived when Indians were outnumbering European colonists in North America, and studying history is not as important than learning sports, and to learn to agree with one’s peers, in American schools.

Colbert started his career, and this is overlooked, overlooking the military, at the grand old age of 21. Colbert branched off into economy and finance much later, after helping to send the hyper rich “superintendent of finances”, Fouquet, to jail, for life.

The American economist Paul Kennedy, in a book about The Rise And Fall Of The Great Powers, basically expounded, as his theory, what was pretty much Colbert’s theory and practice(unsurprisingly, Kennedy does not talk about Colbert too much, and got rewarded with a prize for his depth and originality).

Colbert had perfectly understood that Great Power status necessitated a Great Economy. Thus Colbertism could be viewed as the highest form of militarism. Just like the USA is itself the highest form of militarism which ever was. Notice the rapprochement. Not to make fun of it: the position of Europe and the USA is unstable, just as the entire world economy, society and military situations are all simultaneously unstable, and military superiority is what keeps thing together, right now (unfortunately it is courting defeat in Afghanistan).

Colbert was actually following the model implemented, with spectacular success, by Henri IV and his economy and finance minister, Sully, a protestant military engineer, around 1600 CE, with state financed canals, silk factories and free markets.

Why are great powers great powers? Because they have achieved a technological superiority gradient, and have enough numbers to sit on top of it. Numbers are not everything: the Mongols carved the world’s largest empire in a few years, and with 200,000 warriors. “Technology” here is meant in the full etymological sense: any specialized discourse.

If we want to keep a superior lifestyle in the empire of the West, and a stable planet, it is high time to recover such a gradient, which is, basically, an intelligence gradient. Thus it is high time to redistribute the sort of economy which makes the military industrial complex of the USA so superior, namely COLBERTISM MODERNIZED.

***

The full article is here

Well worth reading.

By Paul Handover

Deregulation – an expert’s view.

Once again, not everything is as it seems!

Focus warning!  This is a longer piece that usual but also a more important piece than usual.  Please find the time to read it and explore the links.  Thank you.

Many, many years ago I lived in Tamarama Bay, just East of Sydney,

Bronte Beach, Australia

Australia.  It was a very short walk to Bronte Beach which was much better experience than the famous Bondi Beach about half a mile North of where we lived.

Thus when I saw the name Bronte Capital it caught my eye because of old resonances from the word “Bronte”.

OK, to the point!

John Hempton is a principle at Bronte Capital, an Australian fund manager.  John is no slouch having been in his past a Chief Analyst for the New Zealand Treasury and Executive Assistant to the CEO of ANZ Bank in New Zealand.  John’s CV is here.

Bronte Capital have a Blog – well who doesn’t – and it was a link to that Blog from Naked Capitalism that caused me to read a recent article from John about deregulation.

Despite me not understanding many of the technical aspects, it struck me with some force, so much so that I wanted to reproduce chunks of it on Learning from Dogs.  John was gracious enough to give me written permission to so do!  Thanks John.

The article is called A Deregulation Conundrum.

John opens by writing:

I have just read Daniel Amman’s excellent biography of Marc Rich – the oil trader notoriously pardoned by Bill Clinton.  I don’t want to get into the politics and ethics of the pardon other than to note that few things in it are black-and-white when you finished reading the book.

and a couple of paragraphs later explains that Marc Rich has a rather appropriate surname – well this is how John writes:

Marc Rich exploited price fixing/import/export controls to make simply unbelievable profits trading oil.  Marc Rich & Co (the Swiss vehicle) was started with just over $1 million in capital and a couple of years later was making in excess of $200 million in profit.  This level of profitability exceeds – by far – any other trading operation I have ever seen – and was probably the most profitable trading operation in history.  Marc Rich & Co (since renamed Glencore) is possibly the most valuable business in Switzerland within the lifetime of its founder.

Just stop here for a moment.

This man, Rich, goes from one million dollars in capital to two hundred million dollars in profits in 2 years, give or take!  Read on:

A typical Marc Rich & Co trade involved Iran (under the Shah), Israel, Communist Albania and Fascist Spain.  The Shah needed a path to export oil probably produced in excess of OPEC quotas and one which was unaudited and hence could be skimmed to support the Shah’s personal fortune.  Israel – a pariah state in the Middle East – wanted oil.  Spain had rising oil demand and limited foreign currency but was happy to buy oil (slightly) on the cheap.  Spain however did not recognise Israel and hence would not buy oil from Israel – so it needed to be washed through a third country.  Albania openly traded with both Israel and Spain.  Oh, and there is an old oil pipeline which goes from Iran through Israel to the sea.

So what is the deal?  The Shah sells his non-quota oil down the pipeline through Israel and skims his take of the proceeds.  Israel skim their take of the oil.  Someone doing lading and unlading in Albania gets their take and hence make it – from the Spanish perspective – Albanian, not Israeli oil.  The Spanish ask few questions.  The margins are mouth-watering – and they all come from giving people what they really want rather than what they say they want.  We know what the Shah wanted (folding stuff).  We know what Israel wanted (oil).  We know what Spain wanted (cheap oil).  Who cares that Spain was publicly spouting anti-Israel rhetoric.  [Similar trades allowed South Africa to break the anti-Apartheid trade embargoes.]

John explains:

It also helped that Marc Rich & Co was a (highly) multilingual firm.  Rich is fluent in Spanish (it is the language he talks to his children in).  He speaks English, German, Yiddish and presumably Hebrew.  His business partner (Pincus Green – pardoned the same day as Rich) speaks Farsi amongst many other languages.  They could do this deal because they could negotiate it and – deep in their heart they hold the Ayn Rand view that trade is a moral virtue and hence they do not need to be concerned with other morality. [The only line that matters is the law – and then it might not be the law of his adopted country – Switzerland – rather than the United States where he was resident.]

My italics, by the way.  Just stay with me for a short while longer to ‘get’ John’s important message.  Here’s John again:

The regulatory regime for domestic American oil was also perverse.  Old oil (meaning wells drilled before the first oil crisis) received one price.  New oil (wells drilled after the crisis) received a higher price.  Squeeze oil (oil that was extracted from wells that ran less than 10 barrels per day) received a higher price still.  The oil could be chemically identical and the price difference over $20 per barrel.  Obviously a trader with a method (any method) of changing the oil source could make a fortune.  Again I am not commenting on legality or morality.  That was just plain fact.  Ayn Rand applies – you give a value and you receive a value.

What all this regulation did was that it allowed people to make simply grotesque profits by thwarting regulation.  The regulation thus worked less well and it was socially unfair.  Pincus Green was good at negotiating in Farsi.  He was astoundingly brave going to Iran immediately after the Shah fell.  He was good at organising shipping.  He worked really hard – but he did not invent something that changed the world and he wound up a billionaire.   Traders make money by intermediating real business solutions – but these were real business solutions to problems made by legislation.  Bad regulation, moral indignation about “trading with the enemy” or “trading with Israel” or with racists in South Africa made people with Ayn Rand morals exceedingly wealthy because you could arbitrage your way around any of these regulations.

OK, you are probably getting the drift of this important article from John.  If any of this ruffles your hair, then read it all – it’s a very important message.  This is what John is saying:

As a plea then I want a debate about the right form of regulation – a regulation that controls agency problems but does not allow arbitrage opportunities to people with “Ayn Rand morals”.

We are not going to get that from the current Tea Party Republicans.  They simply argue that regulation (they say but do not mean all regulation) impinges on “freedom” (something that is clearly a good but hard to define).  However many of the same people want planning regulations to ban a mosque in downtown New York because it is an insult to the victims of 9/11 (and banning mosques is not a restriction on “freedom”).

If that is the level of debate we are not going to get good re-regulation – we are just going to get pandering to whichever lobby group manages to garner most support.  And that is a real risk because we will leave agency problems in place (they benefit the rich and powerful) and we will introduce the same sort of (dumb) regulation that made Marc Rich and Pincus Green astoundingly wealthy.  That sort of regulation also benefits the rich and powerful – especially those with “Ayn Rand morals”.  [The rich and powerful – if you have not noticed – are good lobbyists.  Unless we are careful many amongst them will get their way.]

You didn’t rush those last three paragraphs, did you?

John concludes thus:

I don’t know how to do this well – but I thought I would state the obvious.  The most obvious things that need regulation are things with a government guarantee (implicit or explicit).  If you have an implicit guarantee (as we now know almost all large financial institutions have) then regulation really matters.  If there are large agency problems (small shareholders, large management) then regulation should be deliberately biased to put power in the hands of shareholders not managers (eg banning staggered board elections).

Likewise other agency problems should be strongly policed and the regulation should be of the form that allows that policing.  When Elliot Spitzer found that Marsh – a large insurance broker – was participating in bid rigging against schools buying insurance that was shocking – and is precisely the sort of thing in financial markets that should be policed strongly.  But it took Elliot considerable effort to find and prove his case.  The rules should be established so that sort of behaviour is really difficult to hide.

And I do not think that I need to explain to anyone how much mortgage brokers contributed to the crisis by (a) deliberately misleading borrowers about conditions on their mortgage and (b) participating in the faking of borrowers income/assets/education level when they on-sold the loans to Wall Street.  Agency problems were at the core of the crisis.

On the other side if there is no agency problem then deregulation should remain the order of the day.  Trade restrictions create arbitrageurs – and the arbitrageurs ensure the trade restrictions don’t work anyway.

There are obviously going to be extensions to this rough rule – and this post is really to garner discussion.  But for a start I expect agents who benefit from their agency (and the abuse of their agency) to join the Tea Party.

It is difficult to get policy right.  And when and if the policy is got right we are in for a very long fight to implement it.

I take my hat off to Mr John Hempton. He’s in the ‘finance’ industry, probably doing well, and yet he has the courage to hold a mirror up to the desperately immoral happenings going on around him.

It’s a real pleasure and honour to publish this Post.

Let me close with a short piece from the Sydney Morning Herald of the 2nd January, 2010.

John Hempton ... blog locally, act globally. Photo: Domino Postiglione

WHEN John Hempton started a blog as he recovered from pneumonia, he did not expect to send shockwaves through the finance industry.

But that is exactly what the 42-year-old fund manager did through his Bronte Capital blog. His exposé of an unrelated US hedge fund would eventually lead to $426 million in investments being frozen and authorities seizing control of the Albury fund manager Trio Capital shortly before Christmas.

Fabulous! I salute you, Sir.

By Paul Handover

Statistical impressions!

Or as I would prefer to call it: Lies, Damn Lies and Statistics!

From time to time, I have mentioned David Kauders of Kauders Portfolio Services

I was a client for many years but had to terminate that client relationship when residence in the USA became highly likely!  Very happy with the service and advice provided – extremely so!  (I have no relationship at any level with that firm now!).

Anyway, David publishes what he calls Contrary View from time to time.  His latest is reproduced with his permission.

No. 074 9th August 2010 A statistical impression

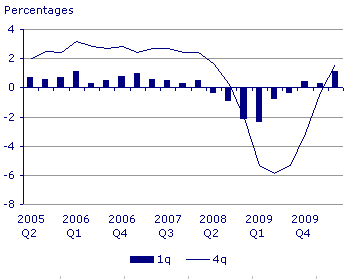
Over the last few weeks a number of graphs have appeared showing how the economy has apparently picked up to where it was before the credit crunch started. Such graphs invariably show a ‘U’ shaped curve demonstrating perfect recovery. This is the impression easily formed by a glance at such a graph, but it is the wrong assumption to make.

National Statistics reports Gross Domestic Product (GDP) as two different measures, both estimates showing a decline in GDP.  Here are the latest figures (estimated), taken from their website last week:

3rd Qtr 2008 Index 102.6

2nd Qtr 2010 Index  99.0

This GDP index shows a permanent loss of output.

Detailed figures are also available (Table 1.02 of the UK economic accounts) and on the same estimating basis, seasonally adjusted, report:

3rd Qtr 2008 GDP £340,780 million

2nd Qtr 2010 GDP £328,766 million

No matter how you look at these figures, there has been a permanent loss of output of just over 3.5% in this period.

This loss of output means less work, so debts are more difficult to service.  Why do the press produce graphs showing an apparently perfect recovery? The answer is that the graphs are taken from the National Statistics press release, for example on 23rd July 2010. The graph that is offered is a rate of change, not the level of output, and may simply have been copied without consideration of the impression formed.

The graph mentioned in the text. Ed.

http://www.contraryview.co.uk, published by Kauders Portfolio Management

WARNING: The firm can only be responsible for action taken on our advice given personally and specifically to be suitable for each individual. Statements on this site do not, on their own, constitute advice. Please note that UK regulatory requirements prevent us commenting on your existing investments or giving specific advice, unless you first sign one of our portfolio service agreements.

As I mentioned in a comment to a regular reader of Learning from Dogs:

To me, sufficiently old to have watched Governments for some decades now, the most striking thing about the present circumstances is the terrible decline in political integrity.

By Paul Handover