Category: Finance

The end of an era, part one.

A review of David Kauder’s recently published book, The Greatest Crash.

Details of the availability of the book are included at the end of both parts of my review, part two is published tomorrow.

Extracts from the book included are with grateful thanks to Sparkling Books.

Personal introduction.

Back in the late 90s, when I was living in England, I attempted to bolster my self-employed income by investing and trading in equities. It was a frustrating game, game being the right word! One day I was lamenting this to a close friend and he gave me the name of David Kauders at Kauders Portfolio Management and suggested I might like to contact him.

I followed my friend’s recommendation and met with David. What he outlined at that meeting all those years ago was mind-blowing, no other way of putting it. Essentially, David predicted a financial and economic crisis of huge proportions. He convinced me of the likelihood of that crisis and in November 2001 I became a fee-paying client. As the world now knows that prediction came to fruition. My anticipated residency in the USA meant continuing to be a client was not possible, and I ceased being a client of Kauders Portfolio Management in June 2010.

Thus not only am I deeply indebted to my friend for referring me to David but also unable to write this review from an unprejudiced point of view.

The Greatest Crash

The book, released in paperback in England in October 2011, published by Sparkling Books, is subtitled ‘How contradictory policies are sinking the global economy‘. Frankly, that subtitle doesn’t do much for me. A clearer message that comes from the book is this: the economic world has reached a ‘systems limit’. Indeed, the term systems limit is used widely throughout the book.

In his introduction to the book, Professor D. R. Myddelton, Chairman of the Institute of Economic Affairs, writes,

Adam Smith said ‘There’s a deal of ruin in a nation’, and it would be a mistake to despair. But one of the things we need now is new thinking on the fundamentals. That is what David Kauders provides in his book ‘The Greatest Crash’.

Without doubt, David achieves that.

Starting with the first sentence, David sets out the core problem;

This book argues that it is impossible to expand the financial system much further.

expanding this a few paragraphs later,

This is the financial system limit: lack of new borrowing plus excessive weight of debt obligations from past borrowing combine to slow economies down. This is the barrier whichever way policy makers turn. It is like the lid on a boiling kettle. Enough steam can lift it for a while but it always snaps back into place. The financial system limit is a roadblock preventing growth.

A few pages later in this opening chapter ‘The roadblock preventing growth‘ this limit is explained thus,

Policy contradictions also show us that the financial system has reached a roadblock. The glaring conflict between bailout and austerity is at the core. Each bailout or stimulus requires creation of more credit, leading to false financial speculation, and for a short while markets recover their poise. The threat of inflation returns. Later, bad debts rise, the markets tumble again and a new crisis emerges. Austerity, the alternative policy, cuts spending thereby cutting the immediate level of economic activity and bringing economic decline more quickly than the stimulus alternative. Whichever way they turn, the authorities are damned.

In the next chapter, ‘Evolution by trial and error‘, David writes about economic cycles and reminds his readers that the long economic cycle is often “beyond the practical experiences of our working lifetimes“.  Then later suggesting that because we have seen the greatest period of inflation ever since the end of World War Two, ergo “the unwelcome lesson from history is that the greatest deflation should follow.”

In Chapter 4, ‘An Era of Wishful Thinking‘, the spotlight is put on the horrific policy errors that have been made for decades, try these three examples (there is a longer list in the book),

  • Policy makers believed that debt could expand indefinitely, at no cost.
  • Nobody realised that interest rate rises would make existing borrowing unaffordable and cause a wave of defaults.
  • The world was swamped with so many detailed requirements and standards that nobody could understand how they all fitted together. It was assumed that ‘transparency’, i.e. extensive detail, would solve the inability to comprehend how the parts made the whole.

Part Two of the review, continuing with Chapter 5 is tomorrow.

Want to buy The Greatest Crash?  The ebook was published in October worldwide, the  paperback published in the UK on the 1st November UK, the hardcover being released any day now in the UK.  For North America both the paperback and hardcover versions are being published on 1st February, 2012.

Full details from the Sparkling Books webpage here.

Copyright © 2011 Paul Handover

Consequences

Acceptance of what has happened is the first step to overcoming the consequences of any misfortune. 

William James, January 11th, 1842 - August 26th, 1910

The above is a quotation attributed to the late American philosopher, William James, comprehensively written about on the Stanford Encyclopaedia of Philosophy.

When drafting this post last Wednesday, I used the quotation and reference to William James to soften, as it were, me reproducing an item on Yves Smith’s fabulous blog, Naked Capitalism.

I did have second thoughts about including the video below and the summary of what was written by Yves.  The second thoughts were around me not wanting Learning from Dogs to stray into sensationalism or hot pop topics.

The reason I did publish this post was that maybe, just maybe, young Mr. Alessio Rastani is saying it how it really is.  How we all have been lulled over the years into believing so much rubbish from so many movers and shakers in the world of power and politics.  Whereas, in truth, most people who stop and reflect on the world we are presently living in, intuitively sense, that something has broken.

The good news that may be interpreted from Mr. Rastani’s predictions is that we are now living through a period of change, the end of an era, and that the opportunity for a better, more caring world is wide open.

Introduced on the Naked Capitalism site, as follows,

This segment on BBC may not go viral, but it seems to be getting traction, based on the e-mails (hat tip readers Paul S and Marcus) and alerts in the comments section.

This is not an entertaining Rick Santelli-style rant, it’s a cool assessment of how the Euromarket crisis is likely to end, which he thinks is very badly. The flummoxed reaction of the BBC host suggests that the trader, Alessio Rastani, was a booking mistake.

But consider his second message: that Goldman and people rule the world and like him don’t care about what happens to the real economy. A depression is just a great investment opportunity if you see it coming and position yourself accordingly. Rastani is the bland, reasonable face of predatory capitalism.

But in the best interests of scepticism and balance, I also reproduce what was published in the UK’s Telegraph newspaper on the 27th September,

11:50PM BST 27 Sep 2011

The soundbites won Mr Rastani instant fame. He became a viral hit and was trending on Twitter. BBC business editor Robert Peston was among the fans. “A must watch if you want to understand the euro crisis and how markets work,” he told his army of 82,000 followers on Twitter on Tuesday.

The interview contained such gems as “Governments don’t rule the world, Goldman Sachs rules the world [and] Goldman Sachs does not care about the rescue package.”

But on Tuesday night the BBC was left facing questions about just how qualified Mr Rastani is to speak about the markets.

In the interview Mr Rastani described himself as an independent trader. Elsewhere he claims he’s an “investment speaker”. Instead of operating from a plush office in Canary Wharf Mr Rastani works and lives with his partner Anita Eader in a £200,000 semi in Bexleyheath, south London. The house, complete with a mortgage from Royal Bank of Scotland, belongs to her not him.

He is a business owner, a 99pc shareholder in public speaking venture Santoro Projects. Its most recent accounts show cash in the bank of £985. After four years trading net assets are £10,048 – in the red.

How a man who has never been authorised by the Financial Services Authority and has no discernible history working for a City institution ended up being interviewed by the BBC remains a mystery.

The incongruity led to some commentators speculating Mr Rastani was a professional hoaxer. The BBC denied the allegation: “We’ve carried out detailed investigations and can’t find any evidence to suggest that the interview with Alessio Rastani was a hoax.”

However, the BBC declined to comment on what checks, if any, it had done prior to the interview.

Mr Rastani was a little more forthcoming.

“They approached me,” he told The Telegraph. “I’m an attention seeker. That is the main reason I speak. That is the reason I agreed to go on the BBC. Trading is a like a hobby. It is not a business. I am a talker. I talk a lot. I love the whole idea of public speaking.”

So he’s more of a talker than a trader. A man who doesn’t own the house he lives in, but can sum up the financial crisis in just three minutes – a knack that escapes many financial commentators.

“I agreed to go on because I’m attention seeker,” he said on Tuesday. “But I meant every word I said.”

We shall see.


What is it you don’t understand?

Stating the obvious.

I am about a third into Paul Gilding’s book The Great Disruption.  It’s proving to be a very-thought provoking read that I will review in more detail over the coming weeks.

However, I just wanted to quote from the start of Chapter 5, Addicted to Growth,

Indeed, as argued by economist Kenneth Boulding: “Anyone who believes exponential growth can go on forever in a finite world is either a madman or an economist.”

Very little that can be argued about that statement.  It rather puts into context a couple of items read recently. Both from the blogsite New Economic Perspectives.  The first on June 10th by Stephanie Kelton,

Earlier this week, President Obama talked about the weakening state of the economy, telling us that he’s not worried about a double-dip recession and that the nation should “not panic.” It’s hard to imagine a more alarming assessment at this juncture.

The recovery is faltering. Our economy is growing at annual rate of just 1.8 percent. Manufacturing just grew at its slowest pace in 20 months. More than 44 million Americans – one in seven – rely on food stamps. Employers hired only 54,000 new workers in May, the lowest number in eight months. Jobless claims increased to 427,000 in the week ended June 4. The unemployment rate rose to 9.1 percent. Nearly half of all unemployed Americans have been without work for more than 6 months. About 25% of all teenagers who are looking for work are unemployed. Eight-and-a-half million Americans are underemployed – i.e. working part-time because their hours have been cut or because they can’t find full-time work. There are, on average, 4.6 unemployed people for every 1 job opening. And even if all the open positions were filled, there would still be 10.7 million people looking for work.

The second on July 8th by Marshall Auerback,

Today’s unemployment data suggests that we are experiencing something far worse than a mere “bump in the road”, as our President described it last month.  In fact, if last month was the time to panic, as Stephanie Kelton argued here, then today’s data should create real palpitations in the White House.  This isn’t just a “bump,” but a fully-fledged New York City style pot hole.

First the headline number everyone looks at: non-farm payrolls. Up 18,000 in June, the increase was 100,000 less than expectations.  In addition the prior two month payroll increases were revised down by -44,000 overall.  That’s weak – but not terrible.

Dig a bit deeper into the data and it looks absolutely awful:  The household measure of employment fell by -445,000.  Okay, it’s a noisy number. But, as Frank Veneroso has pointed out to me in an email correspondence, this measure of employment which is never revised now shows no employment growth over the last five months and very negative employment growth over the last three.

But it gets worse:  The work week was down one tenth.  Overtime was down one tenth.  The labor participation rate at 64.1% was the lowest since 1984.  The broad U6 unemployment rate rose from 15.8% to 16.2%.  In other words, as Frank suggested to me this morning, “many other employment indicators in this report confirm the deep disappointment in the payroll series and the much more negative message of the household series.”

Now here’s the latest item published by Paul Gilding in his Blog, The Cockatoo Chronicles. (I have republished it in full, hopefully without upsetting Mr. Gilding – couldn’t see advice on reproduction – but copyright remains, of course, fully with Paul Gilding.)

Like a Grenade in a Glasshouse

June 29, 2011

It’s going to hit hard and it’s going to hurt – made worse because most aren’t expecting it. They think the world is slowly returning to our modern “normal” – steadily increasing growth, with occasional annoying but manageable interruptions. After all, the global recession wasn’t so bad was it? Sure there was pain and things got shaky but Governments responded, bailed out companies, stimulated economies, got things back on track.  While it’s still a bit bumpy, Greek wobbles, US debt, extreme weather, high oil and food prices etc, it’ll work out. It always does….

If only it were so. In fact we are blindly walking towards the next in a series of inevitable system shaking and confidence sapping crises, deluded in the belief that the worst is behind us.

Each crisis will be a little worse than the last. Each one will shake our denial a little more. This is what happens when systems hit their limits. They don’t do so smoothly, but bump up against the wall, hitting hard, then bouncing off equally hard. It is the behaviour of a system trying to break through. But if the limits are solid, as is the case with our economic system hitting the limits of the planet – defined by unchangeable physical capacity and the laws of physics, chemistry and biology – then it can’t find its way through. So eventually, when the pain of hitting the wall gets too much, it stops.

Then it will hit. Like a grenade in a glasshouse, shattering denial and delusion and leaving it like a pile of broken glass on the floor of the old economic model. Then we’ll be ready for change.

I’ve been arguing the inevitability of this moment since 2005, mostly inside the business community. Before the 2008 financial crisis hit, the idea was almost universally rejected, with a belief in the indomitable power of globalised markets to overcome all challenges and keep growth on track. Most audiences believed that while markets always wobbled, they also always recovered. My suggestion, that this level of arrogance was the hallmark of empires before they fell, landed on deaf ears. They were the masters of the universe and markets and growth would always reign supreme.

Now the response is different. The financial crisis saw many break off from the pack and start to ask the difficult questions. I now find as I tour the world speaking about The Great Disruption to community gatherings, corporate executives and policy makers that minds are increasingly open. While not the dominant view, the previous confidence in the inevitably of growth has become shaky and the group asking the challenging questions is rapidly expanding.

As I argue in the book, the fundamental cause of what’s coming is resource constraint and environmental breakdown, which when combined with an overstretched financial system and high levels of debt puts unbearable tension into the global economy. While no one can know what event will pull the pin out of the grenade, the underlying pressures make that moment inevitable. Yes, the dominant commentary still blames each individual problem on unique circumstances, but the underlying systemic causes are clear for those who wish to look.

The continued level of denial still surprises me, especially given the pressures driving this are not esoteric and can be measured in clear economic indicators. A good example was recently published by one of the more interesting voices to join the growing chorus that we have a system-wide problem. The legendary contrarian and fund manager Jeremy Grantham is co-founder of the Boston based firm GMO, with over $100 billion of assets under management. So this guy is a solid capitalist and market advocate, pursuing wealth for the wealthy. But he sees the data and is raising the alarm, calling this moment “one of the giant inflection points in economic history” – referring to the end of a 100-year steady decline in commodity prices. His views were echoed by Stephen King, group chief economist at HSBC, who wrote in the FT: “After the biggest meltdown since the Great Depression, economic theory tells us that world commodity prices should not be this high. But they are and the West quickly needs to wake up to this new economic reality. Commodity prices are now permanently higher.”

Grantham provides the detail, pointing out that the 100 year trend of falling prices in the 33 most important commodities, except for oil, were wiped out with a price surge from 2002 to 2010 – a surge even greater than experienced in WW2. We have now reached what Grantham calls the Great Paradigm shift; not a price spike but a new reality. Within this new reality, Grantham says: “if we maintain our desperate focus on growth, we will run out of everything and crash.”

This is why hitting the wall is inevitable – because limits are not philosophies, they are limits. We can understand what to expect – and why the grenade will shatter the glasshouse of economic growth – by going back to how systems behave when they hit their limits. Our economic system first hit the wall in 2008 – that was when The Great Disruption began with food and oil prices hitting record highs and a credit crisis driven by reckless monetary policy pursuing growth at all costs. The resulting recession meant we backed away from those limits (bouncing off the wall), and then borrowed massive amounts of money from our children (think Greece) to try to get the economy moving again.

Now that the global economy is slowly entering a so-called “recovery”, the prices of commodities (representing our use of earth’s resources for food and materials) are on the way up, accelerated, in the case of food, by climate change. Of course if significant growth kicks in, the prices of oil, food and other commodities will surge, this timestarting from near record highs.  Then we will bounce back into recession and prices will back off again. Hit the wall, bounce off. Hit the wall, bounce off. Ouch.

By itself this would pose enough of a challenge to growth. But now we also have the debt we used to get the economy moving again. This debt can only be paid off with significant economic growth – but such significant growth is impossible as outlined above. So the debt itself becomes an enormous additional tension in the system, as argued by Richard Heinberg in his important forthcoming book The End of Growth. With the global economy and ecosystem now both burdened by unmanageable debt, effective global default is only a matter of time.

So we’re living in a glass house with the grenade sitting there for all to see. Who knows what will pull the pin. It could be Greece, a Chinese food crisis, peak oil or any number of other triggers. But it’s coming.

The question to ask yourself is simple. Are you ready?

Back to Kenneth Boulding: “Anyone who believes exponential growth can go on forever in a finite world is either a madman or an economist.”

Precisely!

The Winston Churchill effect?

Forgive me for making this a much shorter contribution but the efforts of the previous two posts took rather a long time!

This is about the debt situation in the United States of America and, as always, Learning from Dogs trying to get to the underlying truth.

It’s from the BBC and it’s a radio programme that is included in this Post.

But why the headline referring to Churchill?  Well in the programme Justin Webb, of the BBC, reminds the world of a characteristic of the American Nation noted by Sir Winston Churchill, “Americans can always be counted on to do the right thing…after they have exhausted all other possibilities.”  (But caution about the precise wording of that quote – see here!)

Here’s the article that accompanied the BBC broadcast, the radio programme is after this article,

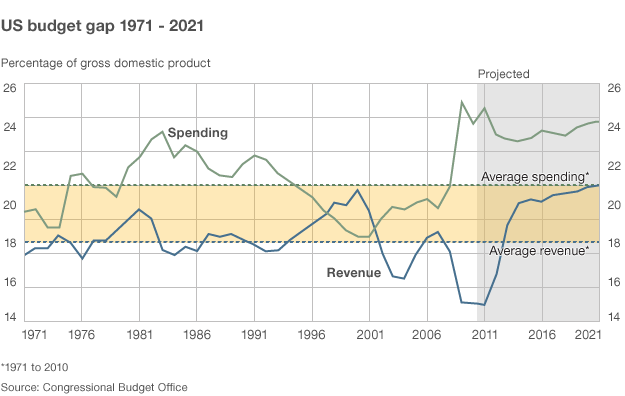
Is the US in denial over its $14tn debt?

Is America in denial about the extent of its financial problems, and therefore incapable of dealing with the gravest crisis the country has ever faced?

This is a story of debt, delusion and – potentially – disaster. For America and, if you happen to think that American influence is broadly a good thing, for the world.

The debt and the delusion are both all-American: $14 trillion (£8.75tn) of debt has been amassed and there is no cogent plan to reduce it.

The figure is impossible to comprehend: easier to focus on the fact that it grows at $40,000 (£25,000) a second. Getting out of Afghanistan will help but actually only at the margins. The problem is much bigger than any one area of expenditure.

The economist Jeffrey Sachs, director of Columbia University’s Earth Institute, is no rabid fiscal conservative but on the debt he is a hawk: “I’m worried. The debt is large. It should be brought under control. The longer we wait, the longer we suffer this kind of paralysis; the more America boxes itself into a corner and the more America’s constructive leadership in the world diminishes.”

The author and economist Diane Coyle agrees. And she makes the rather alarming point that the acknowledged deficit is not the whole story.

The current $14tn debt is bad enough, she argues, but the future commitments to the baby boomers, commitments for health care and for pensions, suggest that the debt burden is part of the fabric of society:

“You have promises implicit in the structure of welfare states and aging populations that mean there is an unacknowledged debt that will have to be paid for by future taxpayers, and that could double the published figures.”

Richard Haass of the Council on Foreign Relations acknowledges that this structural commitment to future debt is not unique to the United States.  All advanced democracies have more or less the same problem, he says, “but in the case of the States the figures are absolutely enormous”.

Mr Haass, a former senior US diplomat, is leading an academic push for America’s debt to be taken seriously by Americans and noticed as well by the rest of the world.

He uses the analogy of Suez and the pressure that was put on the UK by the US to withdraw from that adventure. The pressure was not, of course, military. It was economic.

Britain needed US economic help. In the future, if China chooses to flex its muscles abroad, it may not be Chinese admirals who pose the real threat, Mr Haass tells us. “Chinese bankers could do the job.”

Because of course Chinese bankers, if they withdrew their support for the US economy and their willingness to finance America’s spending, could have an almost overnight impact on every American life, forcing interest rates to sky high levels and torpedoing the world’s largest economy.

Not everyone accepts the debt-as-disaster thesis.

David Frum is a Republican intellectual and a former speech writer to President George W Bush.

He told me the problem, and the solution, were actually rather simple: “If I tell you you have a disease that will absolutely prostrate you and it could be prevented by taking a couple of aspirin and going for a walk, well I guess the situation isn’t apocalyptic is it?

“The things that America has to do to put its fiscal house in order are not anywhere near as extreme as what Europe has to do. The debt is not a financial problem, it is a political problem.”

Mr Frum believes that a future agreement to cut spending – he thinks America spends much too big a proportion of its GDP on health – and raise taxes, could very quickly bring the debt problem down to the level of quotidian normality.

‘Organised hypocrisy’

I am not so sure. What is the root cause of America’s failure to get to grips with its debt? It can be argued that the problem is not really economic or even political; it is a cultural inability to face up to hard choices, even to acknowledge that the choices are there.

I should make it clear that my reporting of the United States, in the years I was based there for the BBC, was governed by a sense that too much foreign media coverage of America is negative and jaundiced.

The nation is staggeringly successful and gloriously attractive. But it is also deeply dysfunctional in some respects.

Take Alaska. The author and serious student of America, Anne Applebaum makes the point that, as she puts it, “Alaska is a myth!”

People who live in Alaska – and people who aspire to live in Alaska – imagine it is the last frontier, she says, “the place where rugged individuals go out and dig for oil and shoot caribou, and make money the way people did 100 years ago”.

But in reality, Alaska is the most heavily subsidised state in the union. There is more social spending in Alaska than anywhere else.

To make it a place where decent lives can be lived, there is a huge transfer of money to Alaska from the US federal government which means of course from taxpayers in New York and Los Angeles and other places where less rugged folk live. Alaska is an organised hypocrisy.

Too many Americans behave like the Alaskans: they think of themselves as rugged individualists in no need of state help, but they take the money anyway in health care and pensions and all the other areas of American life where the federal government spends its cash.

The Tea Party movement talks of cuts in spending but when it comes to it, Americans always seem to be talking about cuts in spending that affect someone else, not them – and taxes that are levied on others too.

And nobody talks about raising taxes. Jeffrey Sachs has a theory about why this is.

America’s two main political parties are so desperate to raise money for the nation’s constant elections – remember the House of Representatives is elected every two years – that they can do nothing that upsets wealthy people and wealthy companies.

So they cannot touch taxes.

In all honesty, I am torn about the conclusions to be drawn. I find it difficult to believe that a nation historically so nimble and clever and open could succumb to disaster in this way.

But America, as well as being a place of hard work and ingenuity, is also no stranger to eating competitions in which gluttony is celebrated, and wilful ignorance, for instance regarding (as many Americans do) evolution as controversial.

The debt crisis is a fascinating crisis because it is about so much more than money. It is a test of a culture.

It is about waking up, as the Americans say, and smelling the coffee. And – I am thinking Texas here – saddling up too, and riding out with purpose.

NB: Copyright BBC © 2011 The BBC is not responsible for the content of external sites. Read more.

Here’s the 30 minute broadcast under the Analysis series from Radio 4 on the BBC.(Just click on this link) analysis_20110628-1024a

Greece, or grease?

The agony of watching a country (and a planet) slip.

Readers will be aware that I very rarely stroll through the tangled pastures of international politics and finance.  The only reason that I do so today is on the back of a very impressive letter published in the German newspaper  Handelsblatt.  That was brought to my attention by my subscription to Mike Shedlock’s (Mish) Blog Mish’s Global Economic Trend Analysis.  You will see that I muse at two levels about where we are today.

Earlier, I had read in last Saturday’s, The Economist a leader on Greece’s debt crisis, entitled Trichet the intransigent.   That started thus,

The European Central Bank’s refusal to consider a restructuring of Greek debt could wreck the euro zone
May 12th 2011 | from the print edition

IF THE stakes were not so high, Europeans’ incompetence in the euro-zone debt crisis would be comic.

and concluded thus,

It is time for the Germans and the IMF to call the ECB’s bluff. Together they should demand, and instigate, a restructuring of Greek debt. Germany should push other European governments to cough up money to support Greek banks and, if necessary, to make whole the ECB. The fund, which knows how to restructure debt, must ensure the process is run in a competent manner. The ECB will then be faced with a choice: go along with an orderly restructuring, or trigger a much greater mess by in effect forcing Greece out of the euro zone. Surely Mr Trichet does not want that to be his legacy.

So with that as background, the letter to Georgios Papandreou, Prime Minister of Greece written by Gabor Steingart is powerful and hard hitting.  Here it is in full.

Mr. Prime Minister,

Dear Mr. Papandreou,

With the greatest respect, the Western world is monitoring your efforts to master your country’s debt crisis. No other democratic country has ever managed anything like that in peacetime. You are shrinking the state apparatus; you are fighting corruption; you are teaching your fellow countrymen how to become honest tax-payers.

You are a modern hero. You are attempting the impossible. As the son of a persecuted and ostracized politician who was chased by the military junta you grew up close to danger. When the officers were looking for your father who was hiding in the attic, they threatened you by putting an unlocked pistol to your forehead and challenged you to betray your father. You denied your father’s presence until he, worried about his son’s life, left his hiding place.Later you fled with him to America where you spent your adolescence. You are alarger-than-life-character.

Preceding governments almost ruined your country. Debts amounting to 340 billion Euros are burdening the Greek state,equaling 155 times the profit of the 60 largest companies of your country and 1.5 times the amount of debts the Maastricht Treaty allows. A year ago, this newspaper, Germany’s biggest Business Daily, appealed to the public to buy Greek government bonds in order to give to the country what Greece needs just as urgently as money: confidence. We also wanted to assist in breaking through the negative spiral of growing doubt and increasing interest rates. Everyone who granted you guarantees and loans wanted it, the European Union, the International Monetary Fund, the heads of state and government.

But since then, the spiral has picked up in speed instead of slowing down. In May 2010 the interest rate at which your country was given money on a ten year basis was at eight per cent. Today, it is at 16 per cent. And in all probability, it will be going up further. The bitter truth to which you and all parties who wanted to help Greece have to admit is that the help doesn’t help. Your country is getting deeper and deeper into the mess. Debts are growing, the gross national product will decrease by at least three per cent in 2011. But it would have to grow by three per cent instead if you were to lower your debt to the allowedlimit until 2040. This is becoming more and more unrealistic. You can’t starve and build up your muscles at the same time.

The truth that Greece has to cut back and save has turned into an untruth. The right thing has turned into the wrong thing. You already cut pensions, lowered the salaries of civil servants by 30 per cent and raised the prices of gas by almost 50 per cent. You can’t restore the health of your country by saving. And the European Union can’t restore your country’s health by again and again injecting new loans.

Soon, the day will come when the tortured body will surrender. The Greek construction industry already shrank by 70 per cent. Sales of car dealers sank by half. A daily export volume of 50 million Euros Greece is achieving  far too little.  Soon the day will come which investors fear in their nightmares. Then the word “insolvency” will be on everyone’s lips.

But it is also the day when a new truth will be born: Don’t save but invest, they will tell you – so that the Greek economy will grow again. Do not service debt with debt, you then will be recommended, but spread out the debt service, cut it and maybe even completely suspend it for a while. It will be a day of impositions, especially for those who lendmoney to you and your people. Financial markets will grind to a halt in horror – and then they will turn to embrace the future. Because Argentina in 2001, Mexico at the beginning of the eighties and Germany after World War II taught us that there is a life after death – at least, in the case of highly indebted states.

Mr. Papandreou, so far, you attempted the impossible. Now you should do the possible. Just as you deceived the officers as a boy and denied to know where your father was hiding you now must repudiate the pride of the Greeks – in order to save your country. Come to meet the new uncomfortable truth before it knocks at your door. It’s already on its way.

Respectfully yours,

Gabor Steingart

The author is an award winning Journalist, the former White House Correspondent of “Der Spiegel” and now Handelsblatt’s  Editor-in-Chief.  His book “The war for wealth. The true story of globalization or while the flat world is broken” was  published in the US, GB, China and several other countries by McGraw Hill, New York, in 2008.

You may contact him at

steingart@handelsblatt.com


Powerful, as I said.

In a sense, in a very real sense, this illustration of the end game of our love affair with debt is symptomatic of the end game in terms of mankind’s love affair with, well with mankind.  The following was written by an inmate of Oklahoma Prison in 1998.

At the root of my humanity lies a potentially insatiable self-centredness.  Given its way, it can become unquenchable. Nothing, not even the richest of imagination, will put out its fire.

This ‘what’s in it for me’ mindset is at the root of all my problems and is where my fears live.  From those fears come anger, greed, intolerance, and a host of other shortcomings.

It is no accident that all religions point to the forgetting of self, because all religions know salvation lies in self-forgetting.

As we head relentlessly towards a level of 400 parts per million (PPM) of carbon dioxide in the atmosphere, 50 PPM above the highest safe limit determined by climate scientists, the time for mankind to move on from the debt-laden, over-leveraged, disconnected life from Planet Earth, is now.

That’s now!

Nature, big business and the future

Just maybe, economic activity and financial capital could align itself with the planetary demands!

A collection of items crossed my screen in the last few days that reinforced the interconnectedness of all life on Planet Earth.

First I saw an item on the BBC News website that demonstrated that climate change, global warming, or however one wants to describe man’s relationship with the planet, is not some crazy, fuzzy idea of a few liberal environmentalists.  This was a report of the significant drop in global wheat yields.

The report was entitled, Climate shifts ‘hit global wheat yields’ and was written by Mark Kinver, Science and environment reporter, BBC News.  Here’s a taste of what was written.

Shifts in the climate over the past three decades have been linked to a 5.5% decline in global wheat production, a study has suggested.

A team of US scientists assessed the impact of changes to rainfall and temperature on four major food crops: wheat, rice, corn and soybeans.

Climate trends in some countries were big enough to wipe out gains from other factors, such as technology, they said.

Professor David Lobell from Stanford University went on to say,

“In particular, you have to assume how non-linear the response will be and how different the crops of tomorrow will be from the crops of today,” he said.

He added that the study focused on historical data in order to strengthen confidence in the existing projections.

“I think it is very clear that climate is not the predominant driver of change over long periods of time in crop production.

“Across the board, you see crop yields going up over the past 30 years, but the question is how much is climate modified (and) what would have happened if the climate was not changing.

“In some countries, we see that climate has only affected things by a few percent. In other countries, we see that yields would have been rising twice as fast.

“On a global average, we see that wheat production would be about 5% higher if we had not seen the warming since 1980. We see about the same for maize or corn.

“Yet for rice and soybean, we actually find that production is about the same as if climate had not been trending.”

The report may be accessed here.

Sort of moving on, most people, when they stop and think about it, must realise that 6.9 billion people living (i.e. depending) on Planet Earth have to be causing changes.  The Inside Science News Service published a reminder from last December of a calculation that,

By Mary Caperton Morton, ISNS Contributor
Inside Science News Service

STRASBURG, Pa. — Next month, representatives from more than 190 nations will gather in Japan at the Nagoya Biodiversity Summit to develop a global strategy for staunching habitat and biodiversity loss around the world.

The statistics are sobering: Every 20 minutes a species goes extinct. At that rate — estimated to be a thousand times faster than pre-human impact background levels – in 300 years, half of all living species of mammals, birds, fish, reptiles and plants will be gone. [My italics]

This alarming decline has not gone unnoticed. In 1992, the United Nations Convention on Biological Diversity — or CBD — one of the most widely ratified treaties in the world, established lofty conservation goals to be met by 2010. But since then the decline in biodiversity has not slowed. Nearly 16,000 species are still listed as threatened, with more than 200 of them described as “possibly extinct.”

What we need, some might ask, is for big business to get behind and push!  Perhaps not so far fetched.

Last October, the British Guardian newspaper, published a very telling reminder that nothing ever in life stays the same.

The article was presented thus,

Biodiversity loss seen as greater financial risk than terrorism, says UN

Loss of ecosystems perceived by banks and insurance companies to be a greater economic risk than terrorism, finds UN report.

Written by Jonathan Watts in Nagoya.

A controlled burn of oil from the Deepwater Horizon well in the Gulf of Mexico. The report cites the Gulf of Mexico oil spill as an extreme example of the potential impact of inadequate environmental controls. Photograph: Ann Heisenfelt/EPA

The financial risks posed by the loss of species and ecosystems have risen sharply and are becoming a greater concern for businesses than international terrorism, according to a United Nations report released today.

From over-depletion of fish stocks and soil degradation caused by agricultural chemicals to water shortages and mining pollution, the paper – commissioned by the UN Environment Programme and partners – said the likelihood has climbed sharply that declines in biodiversity would have a “severe” $10bn (£6bn) to $50bn impact on business.

With the European Union and other regions increasingly holding companies liable for impacts on ecosystem services, it suggests banks, investors and insurance companies are starting to calculate the losses that could arise from diminishing supplies, tightened conservationcontrols and the reputational damage caused by involvement in an unsound project.

Achim Steiner, UN under-secretary general and Unep executive director, said: “The kinds of emerging concerns and rising perception of risks underlines a fundamental sea change in the way some financial institutions, alongside natural resource-dependent companies, are now starting to glimpse and to factor in the economic importance of biodiversity and ecosystems”.

The briefing paper cites the 55% crash of BP’s share price and the decline of its credit rating in the wake of the Gulf of Mexico oil spill as an extreme example of the potential impact of inadequate environmental controls.

Read the full article in the Guardian here.

The United Nations Environment Programme report may be found here.  The cover page says this,

“ As the global financial sector recovers and moves into the post financial crisis era,
there is one notion that crystallises before our eyes more acutely than ever: we need
to understand systemic risk in a much more holistic way. This CEO Briefing underscores
the critical natural capital that underpins our economic activity and financial capital.”
Richard Burrett, Partner in Earth Capital Partners
Co-Chair, UNEP Finance Initiative

Well put!

As I wrote at the very start, just maybe, economic activity and financial capital could align itself with the planetary demands!

The day after April 1st!

When it all gets real close and personal.

I have been a great fan of the BBC’s business editor, Robert Peston, and read his Blog as often as I can.  Recently, the focus has been on Ireland.

A few days ago, before the announcement by the Irish premier and finance minister as to their vision for the future of Ireland’s banks, Robert penned a post that started as follows:

The unbelievable truth about Ireland and its banks
Ireland’s central bank and new government will confirm on Thursday that the hole in the country’s banks is even wider, deeper and darker than seemed to be the case last November, when those bust banks forced the country to go with a begging bowl to the eurozone’s rescue funds and the International Monetary Fund (IMF) for 67.5bn euros (£59bn) of rescue loans.

That article then led me to Paul Mason, BBC Newsnight’s economics editor, who also writes a Blog.  He wrote on the 30th March,

A short summary of the Euro snafu that’s about to happen:

1) Tomorrow Ireland publishes the results of bank stress tests. It has to find – or the EU has to find – another E18-25bn to shore up its failing banks.

etc., etc.

Again, while the article is interesting, the whole point of this Post was one comment made to that Paul Mason piece.  Here it is,

At 00:47am on 31st Mar 2011, tawse57 wrote:

I am bored with all these posts about the economy now. Can we go back to cheese and crackers and the mysterious case of Paul Mason’s mobo contacts?

I was just talking with a 35 year old young man who is married and has a young child.

His wife, quite rightly, does not wish to move away from the place where she was born and brought up – Cornwall.

But he tells me that, despite almost saving £100,000 by putting in every hour they could in working and saving, that they stand no chance of ever owning their own home.

He says the house that he rents have asking prices of about £450,000 despite most of them just sitting on the market for years because no one, no one local anyhow, can afford them. What does sell goes to rich Londoners.

He is destined to pay out most of his wages in private landlord rents. He can’t get into a Council house or a Housing Association property because they either no longer exist or the waiting lists are measured in decades.

He is not prepared to have such a millstone of stress, worry and financial drain around his neck. It would kill him. I don’t blame him.

His story is one of hundreds of thousands, perhaps millions, of people in the UK today.

I mention this as the bank stress tests are directly connected with the massive credit bubble, much of it a housing bubble of liar loans, that brought the global economy to its knees, bankrupted banks and still threatens to bankrupt nations.

All of us on here know this. We are an enlightened bunch.

But I think it is worth remembering that the affects of the global credit binge are still directly affecting so many in this country.

The UK is almost alone in the World in not yet seeing a massive housing crash. The Government and the Bank of England have gone out of their way stop it happening in order to protect the banks who so stupidly, but also so greedily, loaned so many liar loans on bricks and mortar not in other countries but here in the UK.

Those UK banks that keep threatening to leave our shores are up to their eyeballs in global liar loans. You name a country in trouble and you can bet your bottom dollar, which might be the only thing most of us have left soon, that British banks are at the heart of it all.

It is long overdue that this giant house of cards came crashing down. It is long over-due that, as a Society, we cut out the cancer of dirty banks and dirty bankers from our lives and from these shores.

They are leeches on the souls of Men. Gosh, I am getting poetic in my anger. It must be that teaspoon of Jack Daniels I put in my midnight cocoa.

So what if the banks fail their stress tests today, next week or next year. It won’t make a squat of difference to that couple in Cornwall. It won’t make a squat of difference to most of us.

The worst thing that can happen is, as Alistair Darling so panicked, that the ATM machines run empty. Well, what would happen then? Would the sky fall in? Would us polite British all sit at home and do nothing.

Or would we take our cue from the Egyptians, the Tunisians and all the rest?

Perhaps what this country needs most of all is for another even bigger banking crisis? If it happens I think I would feel safer being one of the masses instead of one of the banking elite.

I do hope the banks fail the stress tests. I do hope it brings about another crisis. I do hope that, this time, the People say enough is enough and that this rotting cancer within Humanity is lanced with a fiery lancie thingy.

I could murder a bit of cheese on a nice cracker now.

Whoever you are tawse57, I like your style.  Very powerful words.

“It is error alone which needs the support of government.  Truth can stand by itself.”

~Thomas Jefferson (third President of the United States from 1801 to 1809)

Inside job

The shocking documentary film about the global financial crisis.

I’m sure many have already see the film Inside Job but we only watched it a few nights ago.  Here’s the trailer.

The film is also available to watch on Top Documentary Films and is summarised on that website thus:

As he did with the occupation of Iraq in No End in Sight, Charles Ferguson shines a light on the global financial crisis in Inside Job.

Accompanied by narration from Matt Damon, Ferguson begins and ends in Iceland, a flourishing country that gave American-style banking a try – and paid the price.

Then he looks at the spectacular rise and cataclysmic fall of deregulation in the United States. Unlike Alex Gibney’s fiscal films,Enron: The Smartest Guys in the Room and Casino Jack, Ferguson builds his narrative around dozens of players, interviewing authors, bank managers, government ministers, and even a psychotherapist, who speaks to a culture that encourages Gordon Gekko-like behavior, but the number of those who declined to comment, like Alan Greenspan, is even larger.

Though the director isn’t as combative as Michael Moore, he asks tough questions and elicits squirms from several participants, notably former Treasury secretary David McCormick and Columbia dean Glenn Hubbard, George W. Bush’s economic adviser.

Their reactions are understandable, since the borders between Wall Street, Washington, and the Ivy League dissolved years ago; it’s hard to know who to trust when conflicts of interest run rampant.

If Ferguson takes Reagan and Bush to task for tax cuts that benefit the wealthy, he criticizes Clinton for encouraging derivatives and Obama for failing to deliver on the promise of reform. And in the category of unlikely heroes: former governor Eliot Spitzer, who fought against fraud as New York’s attorney general (he’s the subject of Gibney’s documentary Client 9).

Sony have available on their website a useful study guide.  It appears to be written with students in mind but there is much valuable background information there for all.  The guide, in pdf, may be seen here.

It would all have been worthwhile, if that’s the correct term, if we had seen effective regulatory responses from strong governments but, as the film points out, the millions of people on the receiving end of harsh, downward adjustment of personal wealth are still waiting.

Meanwhile, Europe continues to bleed, American housing is still trending downwards and the real effect of the Japanese earthquake is far from clear.

We are living in interesting times!

Approaches to ‘growth’.

Some thought-provoking articles on the need, or otherwise, of continued growth.

Intellectually, most people, if they stopped and thought about it, would not challenge the absurdity of the notion that a finite rock in space, Planet Earth, can handle an infinite increase in the demands and resources of that finite planetary body, our home in space!

Yet the reality is very different.  For many complex reasons, way beyond the competencies of this writer to fully explain, we, as in the peoples of Planet Earth, continue to behave as though there are no limits to the resources of this beautiful planet that is home for all of us.

Here are some extracts from some recent items that have passed across my ‘in-box’.

A piece from the CASSE website:

What If We Stopped Fighting for Preservation and Fought Economic Growth Instead?

by Tim Murray

Seriously.

Each time environmentalists rally to defend an endangered habitat, and finally win the battle to designate it as a park “forever,” as Nature Conservancy puts it, the economic growth machine turns to surrounding lands and exploits them ever more intensively, causing more species loss than ever before, putting even more lands under threat. For each acre of land that comes under protection, two acres are developed, and 40% of all species lie outside of parks. Nature Conservancy Canada may indeed have “saved” – at least for now – two million acres, but many more millions have been ruined. And the ruin continues, until, once more, on a dozen other fronts, development comes knocking at the door of a forest, or a marsh or a valley that many hold sacred. Once again, environmentalists, fresh from an earlier conflict, drop everything to rally its defense, and once again, if they are lucky, yet another section of land is declared off-limits to logging, mining and exploration. They are like a fire brigade that never rests, running about, exhausted, trying to extinguish one brush fire after another, year after year, decade after decade, winning battles but losing the war.

Just read again the sentence, “For each acre of land that comes under protection, two acres are developed, and 40% of all species lie outside of parks.” Powerful ideas.

Anyway, do read the article in full and see if it changes your attitude.  Here’s how it ends.

Sir Peter Scott once commented that the World Wildlife Fund would have saved more wildlife it they had dispensed free condoms rather invested in nature reserves. Biodiversity is primarily threatened by human expansion, which may be defined as the potent combination of a growing human population and its growing appetite for resources. Economic growth is the root cause of environmental degradation, and fighting its symptoms is the Labor of Sisyphus.

The next article is from The Christian Science Monitor writing about how scientists are getting a new idea about the rate of loss of polar ice.

The seasonal cooling effect of light-reflecting snow and ice in the Northern Hemisphere may be weakening at twice the rate predicted by climate models, a new study shows, accelerating the impact of global warming.

By Pete Spotts, Staff writer / January 18, 2011

A long-term retreat in snow and ice cover in the Northern Hemisphere is weakening the ability of these seasonal cloaks of white to reflect sunlight back into space and cool global climate, according to a study published this week.

Indeed, over the past 30 years, the cooling effect from this so-called cryosphere – essentially areas covered by snow and ice at least part of the year – appears to have weakened at more than twice the pace projected by global climate models, the research team conducting the work estimates.

This is a well-constructed article, easy to read with obvious conclusions.  Towards the end, the author writes:

Snow appears to have its maximum cooling effect – reflecting the most sunlight back into space – in late spring, as the light strengthens but snow cover is still near its maximum extent for the year. Sea ice in the Arctic Ocean has its biggest effect in June, before its annual summer melt-back accelerates, explains Don Perovich, a researcher at the US Army Corps of Engineers Cold Regions Research and Engineering Laboratory in Hanover, N.H., and a member of the team reporting the results.

The final article that I want to include is one from the website Foreign Policy. I’m going to take the liberty of reproducing it in full because it strikes me as an extremely intelligent commentary on where mankind is in terms of our attitudes to growth.

Thomas Homer-Dixon
ECONOMIES CAN’T JUST KEEP ON GROWING

Humanity has made great strides over the past 2,000 years, and we often assume that our path, notwithstanding a few bumps along the way, goes ever upward. But we are wrong: Within this century, environmental and resource constraints will likely bring global economic growth to a halt.

Limits on available resources already restrict economic activity in many sectors, though their impact usually goes unacknowledged. Take rare-earth elements — minerals and oxides essential to the manufacture of many technologies. When China recently stopped exporting them, sudden shortages threatened to crimp a wide range of industries. Most commentators believed that the supply crunch would ease once new (or mothballed) rare-earth mines are opened. But such optimism overlooks a fundamental physical reality. As the best bodies of ore are exhausted, miners move on to less concentrated deposits in more difficult natural circumstances. These mines cause more pollution and require more energy. In other words, opening new rare-earth mines outside China will result in staggering environmental impact.

Or consider petroleum, which provides about 40 percent of the world’s commercial energy and more than 95 percent of its transportation energy. Oil companies generally have to work harder to get each new barrel of oil. The amount of energy they receive for each unit of energy they invest in drilling has dropped from 100 to 1 in Texas in the 1930s to about 15 to 1 in the continental United States today. The oil sands in Alberta, Canada, yield a return of only 4 to 1.

Coal and natural gas still have high energy yields. So, as oil becomes harder to get in coming decades, these energy sources will become increasingly vital to the global economy. But they’re fossil fuels, and burning them generates climate-changing carbon dioxide. If the World Bank’s projected rates for global economic growth hold steady, global output will have risen almost tenfold by 2100, to more than $600 trillion in today’s dollars. So even if countries make dramatic reductions in carbon emissions per dollar of GDP, global carbon dioxide emissions will triple from today’s level to more than 90 billion metric tons a year. Scientists tell us that tripling carbon emissions would cause such extreme heat waves, droughts, and storms that farmers would likely find they couldn’t produce the food needed for the world’s projected population of 9 billion people. Indeed, the economic damage caused by such climate change would probably, by itself, halt growth.

Humankind is in a box. For the 2.7 billion people now living on less than $2 a day, economic growth is essential to satisfying the most basic requirements of human dignity. And in much wealthier societies, people need growth to pay off their debts, support liberty, and maintain civil peace. To produce and sustain this growth, they must expend vast amounts of energy. Yet our best energy source — fossil fuel — is the main thing contributing to climate change, and climate change, if unchecked, will halt growth.

We can’t live with growth, and we can’t live without it. This contradiction is humankind’s biggest challenge this century, but as long as conventional wisdom holds that growth can continue forever, it’s a challenge we can’t possibly address.

Thomas Homer-Dixon is the CIGI chair of global systems at the Balsillie School of International Affairs in Waterloo, Canada.

As Rob Dietz of CASSE wrote in a recent email to me, “I’m a big Thomas Homer-Dixon fan.  His book, The Upside of Down, is outstanding.”

“Economic growth may one day turn out to be a curse rather than a good, and under no conditions can it either lead into freedom or constitute a proof for its existence” Hannah Arendt (1906-1975).


Well said, Hannah!

Power of social networks in the area of finance

“The nature and reach of social conversations in the investment arena.”

The above sub-heading is from a recent Post on Naked Capitalism that rather spookily comes hot on the heels of one of my recent musings.  Here’s what I published on the 12th January although I wrote it on the 9th.

In the past opinion and commentary has been in the hands, more or less, of the giant media moguls.  But technology has changed that.  Now more than ever a huge people have access to the Internet.  Indeed, a quick Google search reveals that of a world population of 6.85 billion people, just under 2 billion (29%) have internet access.  In North America that percentage is 77.4% (226 million) and in Europe the percentage is 58.4% (475 million).  I.e. nearly a billion people in just North America and Europe!

My point is that, in a manner never before experienced in human history, the vast majority of us have the ability to read, learn and muse about the critically important issues facing us today, coming to conclusions that carry political weight.  We have almost infinite choice as to where and how we form opinions.

Thus having access, via the internet, to the scribblings of so many wise people may end up giving democracy the boost it really needs in the face of overwhelming powerful plutocratic forces.

Coincidentally, also on the 12th Yves Smith of Naked Capitalism published an article entitled, The 20 most influential blogs in financial media.  You can find that article here.  Here’s a flavour of what was written.

Thanks to Minyanville for publicizing this study by MindfulMoney on the nature and reach of social conversations in the investment arena. But even bigger thanks go to loyal readers and contributors for their frequent comments, leads, and critiques. The success of a blog depends on its community and I am very grateful for all the input so many of you have generously provided.

Perhaps the most interesting finding (boldface ours):

The research confirms the existence of a network of investment super-connectors with extraordinary media influence and reach. These super-connected new influentials are, for the most part, not well established voices in the media but individual bloggers who fiercely champion their independence….In the US, the network functions as the unofficial voice of Wall Street & the US federal bank with no mainstream media players at the centre of the network.

Given how many of these top blogs are critical of the status quo, this map may be hopeful sign that the blogosphere is beginning to become a important channel of discourse outside the reach of the PR machinery of major corporations and government entities.

And rather than publish all the top 20 names, you can see that list here, the top 10 are as follows:

1. Naked Capitalism
2. Infectious Greed
3. The Big Picture
4. Jesse’s Cross Roads Cafe
5. Zerohedge
6. Mish’s Global Economic Analysis
7. Calculated Risk
8. Paul Krugman’s Blog
9. FT Alphaville
10. Ludwig von Mises Institute

Anyone interested in downloading the original report as published on the MindfulMoney website can go to the article here; the link to the pdf, requiring prior registration, is towards the end of the article.  The article opens thus:

Most investors would acknowledge that social media is playing an increasing role in their investment decisions. Yet no-one has mapped the emerging network of influence likely to be playing a crucial part in those decisions.

Until now that is.  MindfulMoney’s ‘Social Finance: The New Influentials” report is aiming to better understand what this network looks like and to see if a number of super connections, so beloved of writers like Malcolm Gladwell, exist.

The research indicates that they do.

As I said, to download the article you need to register first – that link is here.

It’s a very interesting new world that we are living in and one, I pray, that is returning real power to the electorates.